Switching from Pulley? We’re helping hundreds of companies transition quickly and securely. Talk to our team ❯
Switching from Pulley? We’re helping hundreds of companies transition quickly and securely. Talk to our team ❯


A 409A valuation is an independent appraisal that determines the Fair Market Value (FMV) of a private company’s Common Stock for U.S. tax purposes. It helps companies establish stock option exercise prices and support compliance with Section 409A.
If your private company grants stock options to employees, you have probably heard the term 409A valuation.
But what exactly is a 409A valuation? Why does your company need one? How often should it be updated? And why can the value of your Common Stock be significantly lower than the price investors paid in your latest funding round?
Here is what founders, CFOs, finance teams, and equity professionals need to know.
A 409A valuation is an independent appraisal used to determine the Fair Market Value (FMV) of a private company’s Common Stock for U.S. tax purposes. This value is particularly important when a private company grants stock options to employees, directors, or other service providers who are subject to U.S. taxation.
The requirement is not limited to U.S.-incorporated companies. An Israeli or other non-U.S. private company may also need a 409A valuation if it grants stock options to individuals who are subject to U.S. tax, including U.S. employees, U.S. citizens, or other individuals with U.S. tax exposure. In practice, even one relevant option holder may create the need to consider Section 409A when determining the exercise price of that individual’s options.
When granting stock options, the exercise price, commonly referred to as the strike price, generally needs to be at least equal to the Fair Market Value of the underlying Common Stock on the grant date for the option to fall outside the deferred compensation rules of Section 409A.
For a publicly traded company, establishing Fair Market Value is relatively straightforward because its shares have an observable market price. For a private company, however, there is no quoted market price for its Common Stock.
This is where a 409A valuation comes in.
The valuation considers the company’s financial position, business performance and outlook, capital structure, recent transactions, market conditions, and other relevant factors to determine the Fair Market Value of its Common Stock as of a specific valuation date.
A common question is: if investors recently paid a certain price per share, why can’t the company simply use that price as the exercise price for employee options?
The reason is that investors and employees typically hold different types of securities with different economic rights.
In a financing round, investors generally purchase Preferred Shares, which may carry additional rights and protections, such as liquidation preferences, conversion rights, participation rights, or other preferential terms. Employee options, on the other hand, generally provide the right to purchase Common Stock, which does not necessarily benefit from those same rights.
As a result, the price per share (PPS) paid by investors for Preferred Shares is not automatically the Fair Market Value of the Common Stock, and therefore should not simply be used as the exercise price of employee options.
A 409A valuation addresses this distinction. It considers the company’s overall equity value together with its capital structure and the specific economic rights attached to each class of shares to determine the Fair Market Value attributable specifically to the Common Stock.
This is why a company can complete a financing round at one PPS while its 409A valuation concludes on a different and mostly lower value per Common Share.
A 409A valuation may sound like another compliance requirement, but the number it establishes has a very real impact: it helps determine the price employees pay to exercise their options.
Getting that number right matters.
If options are granted with an exercise price below the Fair Market Value of the underlying Common Stock, the affected option holder may face adverse U.S. tax consequences under Section 409A, including accelerated income recognition and additional taxes and penalties.
A properly prepared independent 409A valuation can also provide safe harbor protection. In practical terms, this means that the valuation is presumed reasonable for Section 409A purposes, provided the applicable requirements are met, placing the company in a significantly stronger position to support the exercise price used for its option grants.
The importance of a well-supported valuation can also extend beyond the grant date. As a company grows, its historical valuations and option grants may be reviewed in connection with audits, financing rounds, due diligence, acquisition, or preparations for an IPO.
A 409A valuation is therefore not just about arriving at a number. It is about having a defensible basis for the value used when granting equity to your employees.
Timing is an important part of 409A compliance.
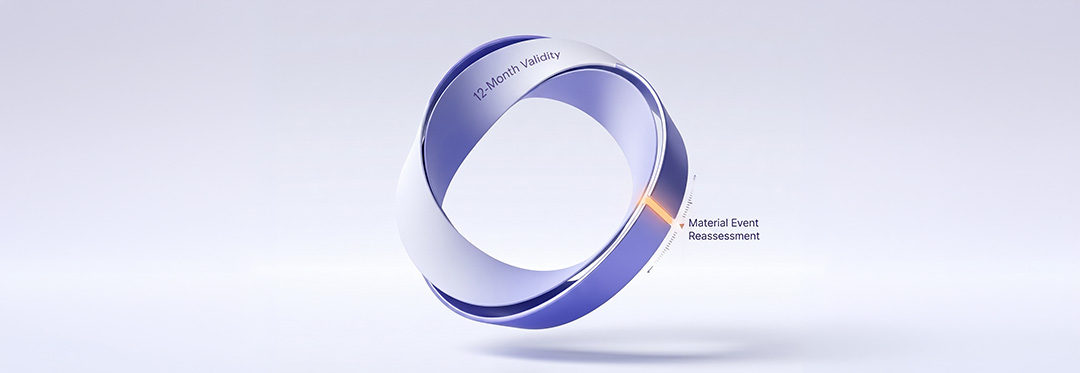
A private company will generally obtain a 409A valuation before granting stock options to individuals subject to U.S. taxation. Once completed, the valuation may generally be relied upon for up to 12 months, provided that no material event occurs that could significantly affect the company’s value.
But the 12-month rule is only part of the picture.
A valuation can become outdated before the end of that period if something significant changes. A new financing round is perhaps the most obvious example, but it is not the only event that may require the company to revisit its Fair Market Value.
Potential material events may include:
· A new financing round
· A significant secondary transaction
· A material change in actual or projected financial performance
· A major commercial or strategic development
· An acquisition or other significant corporate transaction
· A significant change in the company’s capital structure
· Meaningful progress toward an IPO, M&A transaction, or other liquidity event
For example, if a company completed a 409A valuation six months ago but has since raised a significant financing round, the fact that the valuation is less than 12 months old does not necessarily mean it should continue to be used for new grants.
A 409A valuation sits at the intersection of valuation, tax compliance, and equity management. And as a company grows, that intersection can become increasingly complex.
At altshare, the valuation process is not disconnected from the company’s equity management. Our dedicated valuation team works alongside a platform built to manage the cap table, equity plans, grants, financing rounds, and the securities that ultimately form the basis of the valuation analysis.
That combination matters.
One of the most time-consuming parts of a valuation process can be collecting and reconciling the company’s equity information.
When your cap table is managed through altshare, much of the information needed to understand the company’s capital structure is already available within the same ecosystem. Financing rounds, share classes, outstanding options, warrants, SAFEs, and other securities can be reviewed as part of a more connected valuation process.
This means less back-and-forth, fewer disconnected spreadsheets, and a smoother process for finance, legal, and HR teams.
Technology can make the 409A process faster and more efficient but valuation is not simply a data-entry exercise.
Companies may have complex liquidation preferences, multiple financing rounds, secondary transactions, SAFEs and convertible instruments, or different potential liquidity scenarios. Determining how these factors affect the value of the Common Stock requires professional judgment.
At altshare, technology supports the process, while the valuation itself is performed and reviewed by valuation professionals who understand both the financial analysis and the economics of complex capital structures.
Your first 409A may be relatively straightforward. Your next one may not be.
As your company raises additional rounds, introduces new securities, completes secondary transactions, or moves closer to a potential liquidity event, the valuation methodology and level of analysis may need to evolve as well.
altshare supports companies throughout that journey - from their first option grants through increasingly complex capital structures and later-stage valuation requirements.
Ultimately, a 409A valuation should not be another standalone document that needs to be managed separately from the rest of your equity operations.
At altshare, cap table management, equity compensation, and valuation come together in one ecosystem, supported by a team that understands how each piece affects the others.
The result is a 409A process designed to be professional, efficient, and connected to the equity data behind it.
Talk to altshare’s valuation team. We’ll help you understand what your company needs and guide you through the process.
altshare is a leading, fast-growing Equity Management & Compensation Plans Administration solutions provider. We love challenges. We are obsessed with our clients. We are on a mission to redefine the way founders do equity. All our products & services are supported through the altshare Platform - the only equity management platform built for entrepreneurs.